Image from OUE Commercial REIT.
Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
This article was first published on Bondsupermart.com on 14 Sep 2021.
With a high debt load and falling revenues, OUE Limited partially divested their iconic OUE properties to shore up their cash balances and withstand the impact of COVID-19. With lower finance expenses and gearing ratio, this bond offering looks attractive.
If you work in Singapore’s Central Business District, you would have surely heard of or seen properties of OUE Limited (“OUE”). The obvious ones would be OUE Bayfront, OUE Link and OUE Downtown. Other commercial properties also include One Raffles Place and Lippo Plaza in Shanghai. OUE also has hospitality assets – Mandarin Orchard Singapore, which would be rebranded to Hilton Singapore Orchard in 2022, and Crowne Plaza Changi Airport. Its retail arm is supported by Mandarin Gallery and Downtown Gallery and in 2017, OUE ventured into the healthcare sector by acquiring OUE Lippo Healthcare Limited, and subsequently became the manager of First REIT. OUE is also the sponsor of OUE Commercial REIT (“OUE C-REIT”).
(For more details about OUE, read OUE Limited: Credit Update)
OUE is launching 5-year senior unsecured bonds under the terms of the SGD 3b Multicurrency Debt Issuance Programme at an initial price guidance of 3.70%. The proceeds are to be used for general working capital purposes of the group, general corporate funding, and/or refinancing the existing borrowings of the group.
Snapshot of FY20 and 1H21 operating results
Like many other companies, OUE was adversely affected by COVID-19, especially its hospitality segment. Revenue for that segment fell by 64.6% YoY in 2020 with total revenue falling by 43.0% YoY to SGD 530.5m for FY20. The group also provided a total of SGD 19.9m relief measures via rental rebates and assistance schemes for eligible tenants.
Operating profit for 2020 fell by 25.3% YoY to SGD 246.7m but losses after tax came in at SGD 404.8m due to net fair value losses of about SGD 435.4m. This included SGD 298.9m fair value loss in relation to the disposal of US Bank Tower which was derived based on the difference between the sale price and reported fair value of USD 650m as at 31 Dec 19.
In March 2021, OUE partially divested OUE Bayfront, OUE Tower and OUE Link (the “OUE Bayfront Property”) for a cash consideration of SGD 950.6m, with net proceeds at about SGD 262.6m. Due to the sale of US Bank Tower and partial divestment of the OUE Bayfront Property, revenue from the investment properties segment decreased by 24.4% YoY to SGD 105.2m for 1H21. Hospitality revenue (SGD 25.8m) continued to decline (-41.1% YoY) due to the full half-year impact of restrictions.
Operating profit for 1H21 thus fell by 16.5% YoY to SGD 104.4m while profit before tax came in at SGD 65.2m. Due to large fair value losses in 2020, adjusted EBIT would be a better indicator to look at to compare the two periods. It fell by 16.5% YoY to SGD 104.4m in 1H21.
Credit profile
The divestment of their investment properties helped to reduce OUE’s debt load with total borrowings decreasing by SGD 886.3m from end-2020. While its current cash balance of SGD 330.7m is not enough to pay off its current debt of SGD 461.2m, this new debt offering will help refinance its debt, which is likely the OUESP 3.750% 17Apr2022 Corp (SGD) with SGD 200m outstanding. The group also has undrawn facilities of SGD 270m as at 30 Jun 2021.
Its non-current debt of SGD 2.13b is a bigger issue, where SGD 1.23b of it is secured and SGD 900m is unsecured. The majority of its secured borrowings are secured bank loans which OUE should have little trouble refinancing. Its investment properties are currently valued at SGD 4.54b and SGD 2.55b of it are pledged as security for banking facilities as at 31 Dec 2020. Its property, plant and equipment (hotels) are valued at SGD 1.71b with SGD 1.16b of it mortgaged to financial institutions as at 31 Dec 2020.
Its unsecured borrowings consist of unsecured bank loans, outstanding SGD 200m of OUESP 3.550% 10May2023 Corp (SGD) and SGD 250m of OUE C-REIT bonds. Similarly, OUE should be able to refinance its bonds, but if push comes to shove, OUE can partially divest some of its investment properties to build up its cash balances to repay its borrowings.
As its finance costs fell, adjusted trailing twelve-months (“TTM”) interest coverage ratio using EBIT improved from 1.8x in 2020 to 1.9x in 1H21. Net gearing ratio (net debt/equity) also improved from 52.0% in 2020 to 40.6% in 1H21.
Relative valuation
We look at other bonds from property developers and REITS such as Frasers Property Limited, Guocoland, OUECT and Suntec REIT. Suntec REIT has many bonds which allows us to do a better comparison.
Table 1: Credit ratios of OUE, OUECT and Suntec REIT
|
1H21 |
OUESP |
OUECT |
SUNSP |
|
TTM adjusted interest coverage ratio (x) |
1.95 |
2.69 |
2.43 |
|
Net debt/equity |
40.6% |
51.90% |
70.90% |
Source: Bloomberg Finance L.P., companies’ 1H21 financial statements, iFAST compilations
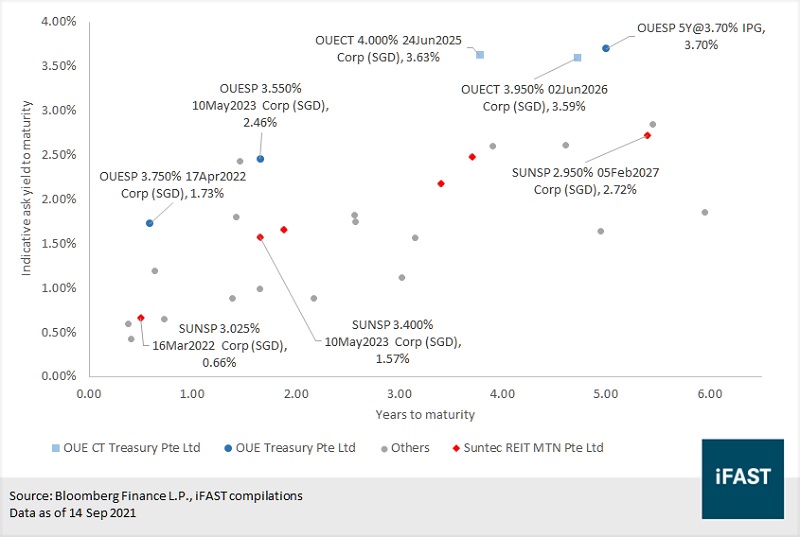
We find the new OUE 5-year bonds to be attractively priced at 3.70%, and will be indifferent between the bonds and the OUECT 3.950% 02Jun2026 Corp (SGD) at a yield-to-maturity (“YTM”) of 3.6%.
Figure 1: Relative valuation of comparable notes using YTM
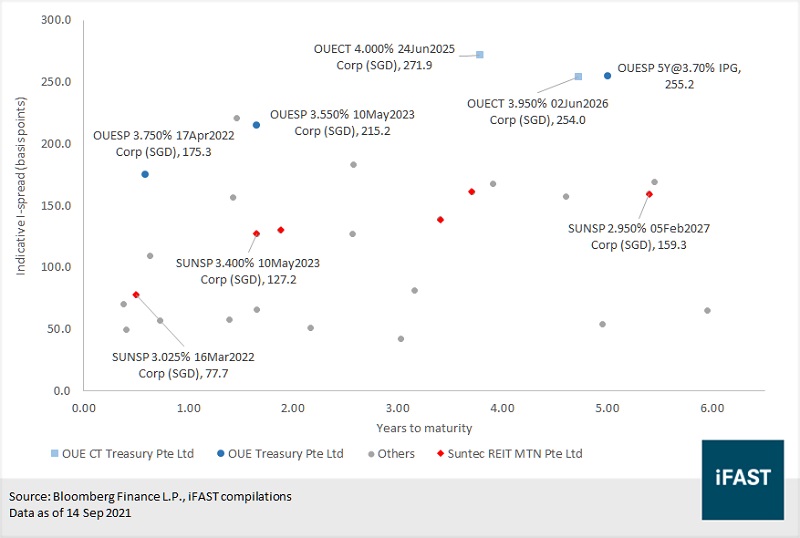
Using I-spread (spread
between the bonds and their SGD swap rates), the existing OUE notes have a
difference of about 90-100 basis points (“bps”) over their Suntec REIT
counterparts with similar years to maturity. With a spread of about 96bps over
the SUNSP 2.600% 27May2025 Corp (SGD), the OUESP 5Y seems to be an attractive
investment.
Figure 2: Relative valuation of comparable notes using I-spread
Declaration: For specific disclosure, at the time of publication of this report, IFPL
(via its connected and associated entities) holds a position in OUECT 3.950% 02Jun2026 Corp (SGD) and OUESP 3.750% 17Apr2022 Corp (SGD)
and the analyst who produced this report holds a NIL position in the
abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!